
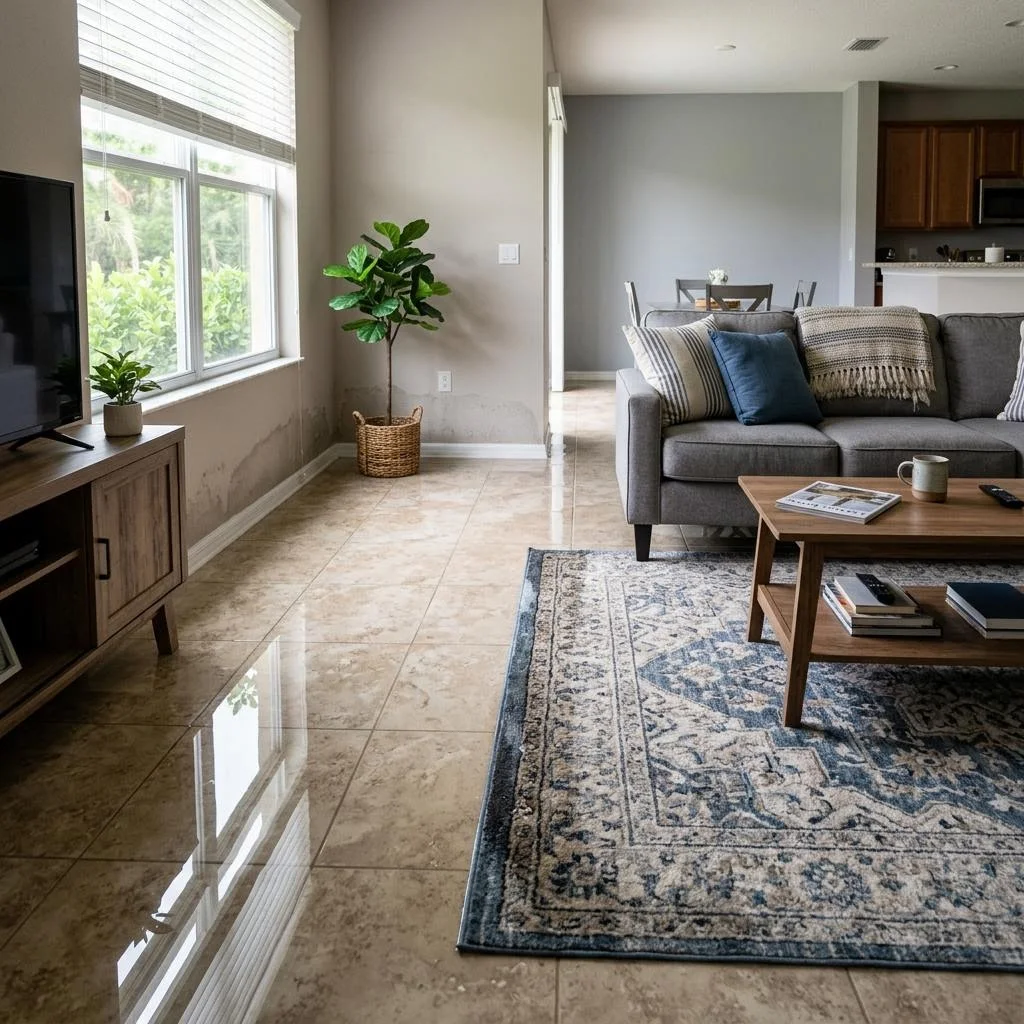
Outside floodwater and a plumbing release can require different source repairs, precautions and insurance questions. Clear water is not proof of cleanliness, and the word “flood” in conversation does not determine an insurance category.
Describe observations rather than labels
Record whether water rose from outside, entered through an opening or appeared near a fixture. Several sources can coexist during severe weather. Do not enter the area to trace the route, and explain uncertainty instead of choosing an insurance label yourself.
Let source and conditions guide the response
Outside water or sewage can introduce contamination concerns. Electrical or structural damage can restrict reentry. A plumber, roofer or other professional may be needed for the source before interior work is safely accessible. Ordinary household fans are not a universal response.
Ask policy-specific questions
Contact your insurer about what reporting and documentation are needed. Outside flooding, backup and plumbing events can be treated differently under actual policy language. A contractor cannot promise approval or tell you that every storm-related water event has the same coverage.